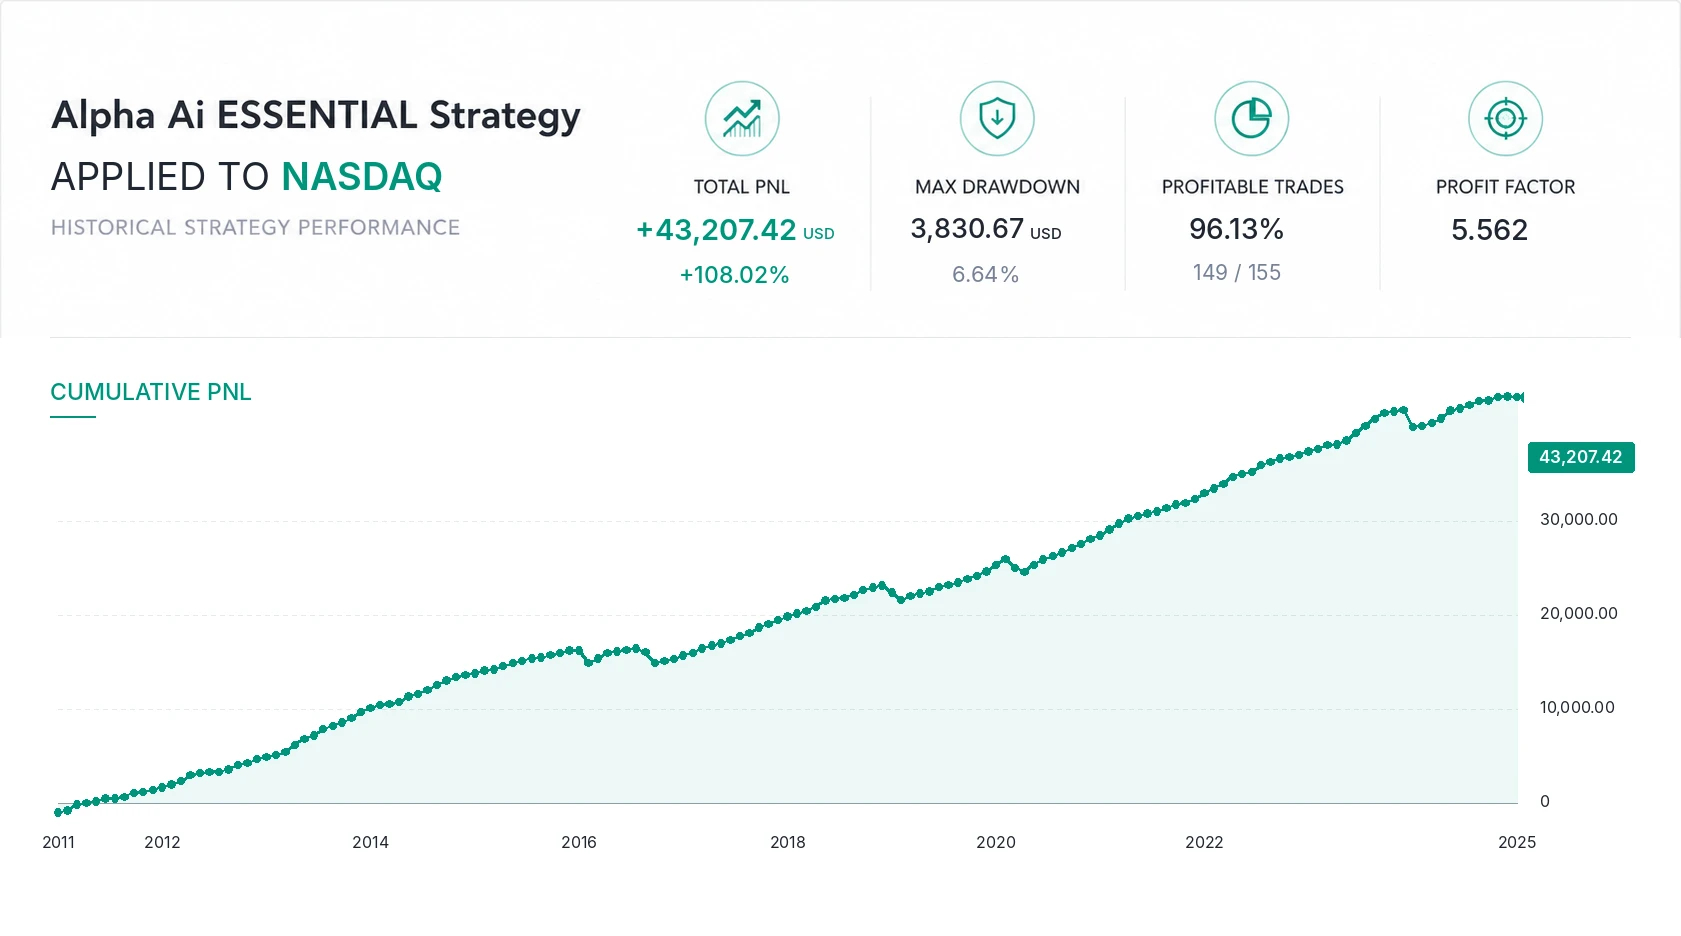
Options vs Margin Trading for Small Accounts
A $4,000 account can usually afford one good trade. The harder problem is preserving diversification when a systematic strategy has many valid positions open at the same time. This article compares margin, long CALLs and debit spreads using Alpha AI trade data.
Which data is actually being used?
The Alpha AI database supplied for this study contains 6,335 records across 84 assets, covering January 2, 2019 through September 17, 2026.
| Dataset | Period | Purpose in this article |
|---|---|---|
| Backtest period | Jan 2, 2019 → Dec 31, 2024 | Historical Alpha AI behavior |
| Live period | Jan 1, 2025 → Sep 17, 2026 | Recent live-period Alpha behavior |
| Full Alpha universe | 84 assets | Portfolio-level context |
| US equity / ETF options research subset | 48 underlyings | Strike, DTE, payoff and capital-efficiency analysis |
The options-specific subset excludes non-US portfolio instruments such as European/Asian listings, indices, commodities and crypto. It is used because PLTR/DHR-style equity options should be evaluated against the trade behavior of the relevant equity/ETF universe, not against every asset Alpha AI trades.
The live period remains strong, but it is not identical to the backtest.
| All Alpha LONG trades | 2019–2024 Backtest | Jan 2025–Sep 17 2026 Live |
|---|---|---|
| Closed BUY trades | 2,415 | 651 |
| Winners | 2,140 | 564 |
| Losers | 263 | 84 |
| Flat | 12 | 3 |
| Win rate, excluding flat | 89.06% | 87.04% |
| Mean winner | +3.59% | +3.56% |
| Median winner | +2.54% | +2.30% |
| Mean loser | −3.80% | −6.65% |
| Median loser | −1.37% | −5.45% |
These figures describe Alpha AI as a whole. They are useful for portfolio context, but the next sections use the narrower US equity/ETF subset when discussing option structure.
A good strategy can still be difficult to execute with only $4,000.
A small account can usually afford one position. The problem appears when a diversified rules-based strategy identifies many opportunities at the same time.
That is why margin and options should be compared at portfolio level, not by looking at one spectacular percentage gain.
Margin reduces the cash required to carry a position. It does not reduce the underlying exposure.
Suppose a stock trades at $200. Buying 10 shares creates a $2,000 position.
Broker margin requirements also vary by account, security and jurisdiction.
A CALL adds strike, premium and expiration to the trade.
A standard US equity option normally represents 100 shares. Instead of buying the shares directly, the trader pays a premium for a contract with a specific strike and expiration.
For a straightforward purchased CALL, the premium paid is generally the maximum amount that can be lost on the option itself, excluding commissions and fees.
Cheaper CALLs are usually cheaper because they require a larger move.
If PLTR trades around $175, a $185 CALL is farther from the market than a $177.50 CALL. The farther strike will usually cost less, but it also needs a larger or faster move to respond strongly.
| Strike | Distance from $175 | Typical characteristic |
|---|---|---|
| $177.50 | +1.4% | Closer / usually more expensive |
| $180 | +2.9% | Intermediate |
| $185 | +5.7% | Cheaper / more aggressive |
The underlying gained +5.78%. The customer's CALL showed +44.01%.
| Alpha AI PLTR trade | Timestamp / value |
|---|---|
| BUY | Sep 11, 2026 · 16:30:16 @ $166.44 |
| CLOSE | Sep 17, 2026 · 19:30:12 @ $176.07 |
| Holding time | 6d 2h 59m 56s |
| Underlying result | +5.78% |
| Alpha stop used for comparison | −14% |
The customer used a PLTR $185 CALL. The screenshot showed +$169 / +44.01%, implying an estimated original premium of about $384.
| PLTR | Stock / Margin | CALL |
|---|---|---|
| Approx. planned/max risk | $384 | ~$384 premium |
| Underlying move | +5.78% | +5.78% |
| Approx. profit | +$159 | +$169 |
| Profit relative to initial risk | ~+41% | +44.01% |
At approximately equal dollar risk, the two outcomes were much closer.
Capital efficiency matters more when the process is diversified.
Alpha AI is applied across 80+ supported markets rather than relying on one ticker to produce the next opportunity.
EXPLORE 80+ MARKETS →A correct directional trade can still produce a weaker option result.
| Alpha AI DHR trade | Timestamp / value |
|---|---|
| BUY | Sep 11, 2026 · 18:30:08 @ $199.93 |
| CLOSE | Sep 15, 2026 · 18:30:23 @ $208.12 |
| Holding time | 4d 00h 00m 15s |
| Underlying result | +4.09% |
| Alpha stop used for comparison | −7% |
The customer traded a DHR $210 CALL and showed approximately +$75 / +22.06%, implying an estimated initial premium of about $340.
| DHR | Stock / Margin | CALL $210 |
|---|---|---|
| Approx. planned/max risk | $340 | ~$340 premium |
| Underlying move | +4.09% | +4.09% |
| Approx. profit | ~+$199 | +$75 |
| Profit relative to initial risk | ~+58.5% | +22.06% |
The relevant option subset behaves differently from the full Alpha universe.
For option-structure research, the analysis uses the 48-underlying US-market equity/ETF subset rather than all 84 Alpha assets.
| US equity / ETF subset | 2019–2024 Backtest | Jan 2025–Sep 17 2026 Live |
|---|---|---|
| Closed LONG trades | 1,236 | 300 |
| Winners | 1,114 | 255 |
| Losers | 119 | 44 |
| Flat | 3 | 1 |
| Win rate, excluding flat | 90.35% | 85.28% |
| Mean winner | +4.25% | +4.83% |
| Median winner | +3.14% | +3.11% |
| Mean loser | −4.57% | −8.58% |
| Median loser | −1.65% | −9.94% |
Most winning equity trades are useful moves — but not enormous moves.
| Winning move in the underlying | Live US equity / ETF winners |
|---|---|
| ≤ +2% | 28.24% |
| ≤ +3% | 48.24% |
| ≤ +5% | 64.31% |
| > +10% | 9.41% |
| Median winner | +3.11% |
| Mean winner | +4.83% |
Almost half of winning live equity/ETF trades gained 3% or less, while roughly two-thirds gained 5% or less.
A very cheap far-OTM CALL may require a move larger than many ordinary Alpha winners actually produce.
DTE should be matched to the equity strategy's actual holding times.
Holding-time statistics use 298 matched live US equity/ETF BUY→CLOSE trades.
| Metric | Live US equity / ETF result | Options implication |
|---|---|---|
| Median holding time | 8.38 days | Typical trades are short, but not ultra-short |
| Closed within 7 days | 45.97% | Less than half close inside one week |
| Closed within 14 days | 69.46% | 14 DTE still leaves meaningful expiration risk |
| Closed within 30 days | 91.28% | Most trades finish inside one month |
| 95th percentile duration | 38 days | A minority require substantially more time |
| Median winner duration | 7.17 days | Winners generally resolve faster |
| Median loser duration | 13.06 days | Losers remain exposed to Theta longer |
How many option positions would a small account actually need to carry?
The full database snapshot contains 21 positions marked Open. Of those, 9 belong to the US equity/ETF options research subset.
To avoid letting one snapshot dominate the analysis, concurrency was also measured across the live period using matched entry/close intervals and a daily end-of-day count.
| US equity / ETF positions open simultaneously | Live-period level |
|---|---|
| Median | 6 |
| 90th percentile | 10 |
| 95th percentile | 12 |
| Observed maximum | 19 |
The concurrency data gives us a practical option-budget range.
Suppose the trader keeps $1,000 in cash and allocates $3,000 to option premiums.
| US option positions | Historical context | Average debit available |
|---|---|---|
| 6 | Median concurrency | $500 |
| 10 | 90th percentile | $300 |
| 12 | 95th percentile | $250 |
| 19 | Observed maximum | ~$158 |
A structure averaging roughly $250–$300 would historically cover most live US-equity concurrency; roughly $160 would be required to cover the most crowded observed period with the same $3,000 allocation.
The PLTR (~$384) and DHR (~$340) customer CALLs are therefore not automatically too expensive. They fit ordinary periods better than extreme crowded periods.
The trade profile narrows the research candidates.
| Structure | Potential fit | Main issue |
|---|---|---|
| Deep ITM CALL | High stock-like behavior | Premium may consume too much of a small account |
| ATM / slightly OTM CALL | Strong research candidate | Must fit the $250–$300 normal-period debit budget |
| Far OTM CALL | Low initial debit | Many +2% to +5% winners may not move enough |
| Call Debit Spread | Strong research candidate | Upside is capped and execution has two legs |
| Very short-dated CALL | Cheap premium | 14 DTE would not cover about 30% of observed live equity holds |
| LEAPS | Low expiration pressure | Potentially inefficient for an 8.38-day median hold |
The data makes ATM/slightly OTM CALLs and Call Debit Spreads the most obvious structures to test first. That is a research priority, not a recommendation.
The database cannot tell us actual historical option returns.
It contains the underlying Alpha entries and exits, not historical option chains. Proper validation requires the actual strike, expiration, bid/ask, implied volatility, Delta and executable option price at each Alpha BUY and CLOSE.
Inspect Alpha AI on your own charts for 3 days.
Understand the underlying entry, risk and exit process first. Options should be treated as a separate execution layer whose performance must be validated independently.
GET FREE 3-DAY ACCESS EXPLORE 80+ MARKETSThey solve different problems.
Do not judge the structures only by percentage return on one trade.
A structure that earns slightly less on one position can still be more useful at portfolio level if it allows several additional diversified signals to be taken without exhausting buying power.
The option layer must earn its own statistical record.
-
Start from the original Alpha BUY timestamp and underlying price.
The option test must use the same signal the underlying strategy actually generated. -
Define the eligible option universe in advance.
Use the same US equity/ETF classification consistently rather than changing the sample after seeing results. -
Set DTE and Delta rules before testing.
Do not choose whichever historical contract happens to have performed best. -
Set a maximum debit per position.
Portfolio capacity is part of the strategy for a small account. -
Close the option when Alpha issues its original CLOSE.
This preserves the underlying strategy's exit logic. -
Measure the whole portfolio.
Compare option-level win rate, average winner, average loser, drawdown, capital usage, signal participation rate, slippage and return per dollar committed.
For a $4,000 account, the answer depends on the constraint you are trying to solve.
If the objective is to reproduce Alpha's underlying trades as faithfully as possible, fractional shares and controlled margin remain the cleaner implementation.
If the objective is to participate in a broader set of simultaneous US-equity Alpha signals with limited capital, options become much more interesting because they can reduce the cash required per position.
The current data points first toward testing ATM/slightly OTM long CALLs and Call Debit Spreads, using fixed DTE, Delta, liquidity and maximum-debit rules. Only historical option-chain data can determine whether either structure actually improves the portfolio.
Want to inspect the underlying process before choosing the execution layer?
Explore the supported market universe, review Alpha AI performance, or request complimentary 3-day TradingView access.
Sources, methodology & further reading
- Alpha AI internal trading database: 6,335 records, 84 assets, Jan 2, 2019–Sep 17, 2026. Backtest period: 2019–2024. Live period: Jan 1, 2025 onward.
- Options research subset: 48 US-market equity/ETF underlyings. Live option-selection statistics use 300 closed LONG trades; holding-time statistics use 298 matched BUY→CLOSE trades.
- Concurrency methodology: daily end-of-day count of overlapping matched live US equity/ETF positions, with currently Open database positions carried to the dataset cutoff.
- PLTR / DHR option examples: customer screenshots. Original option premiums are estimated from displayed dollar profit and percentage return and may differ from actual execution.
- Interactive Brokers — Options Trading: calls, strikes, premiums and expiration
- Interactive Brokers — US Options Margin Requirements
- Interactive Brokers — US Stock Margin Requirements
Trading stocks, margin products and options involves substantial risk. Options can expire worthless, resulting in the loss of the entire premium paid. Margin can magnify losses and may create additional capital requirements. Stops do not guarantee execution at the specified price. Historical and backtested results do not guarantee future performance. This article is educational and does not constitute individualized investment advice.